Official template · basic · Income
Compare call premium alongside risk.
Answer "where is the covered call premium today" with the risk shown next to the yield.
The report UI is recreated from the test app's Sep 25, 2026 session, not a live screen. A historical example with music; no narration.
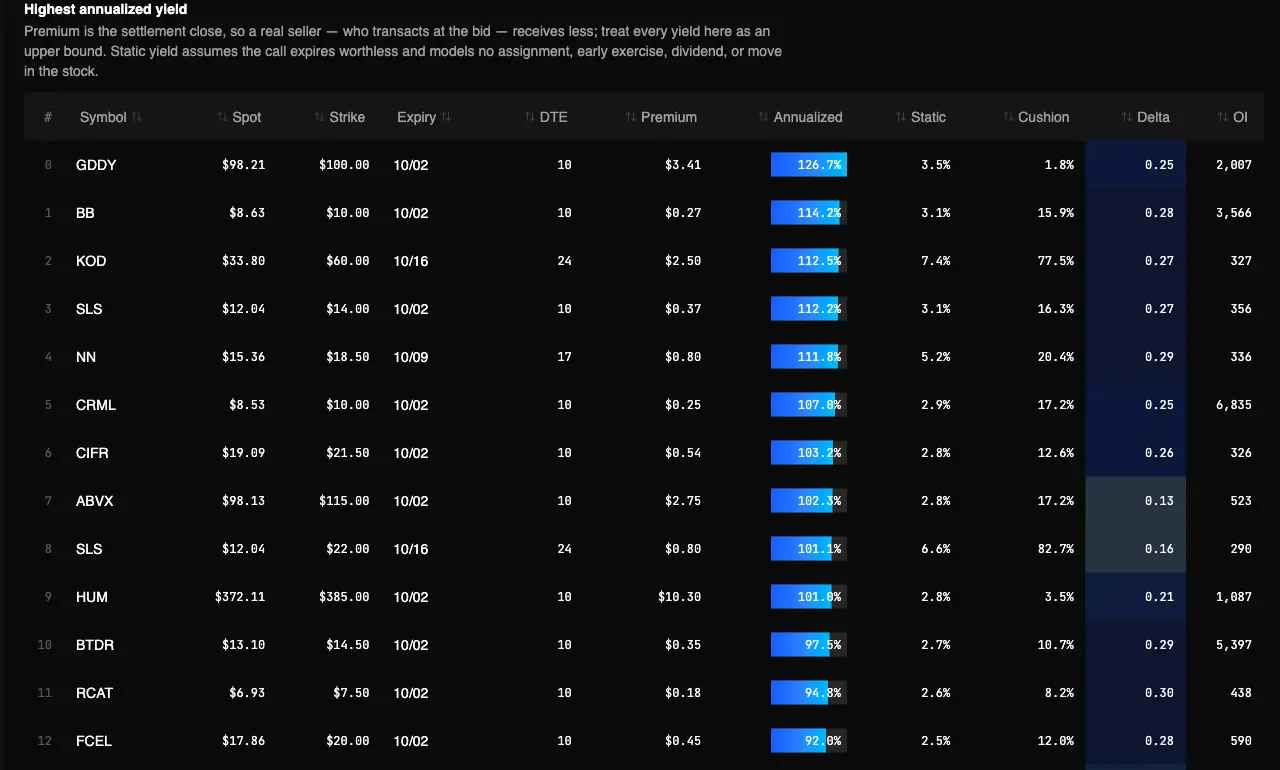
Captured Sep 23, 2026 on testapp.tradingflow.com. This is a historical example; results on this page do not refresh. Swipe across the image to inspect its columns.
- 01Delta + expiry filters
- 02Static yield screen
- 03Calls with risk context
Settlement-close yields are upper bounds, not realized returns.
Read the output
- 01Annualized static yield: premium as a share of spot, scaled to a year.
- 02OTM cushion — how far the stock can rise before the strike is touched.
- 03Delta as the conventional rough proxy for finishing in the money, plus open interest.
Keep in mind
Premium is the settlement close; a seller transacts at the bid, so every yield shown is an upper bound.
How to read it
From report to evidence01
Set the assignment ceiling
Delta caps how far in the money the screen will go.
02
Read yield with cushion
A high annualized number on a thin cushion is a different trade from the same yield further out.
03
Sanity-check the vol
High yield is usually high implied volatility — the market pricing a wider range, not free income.
Method and limitations
A one-screen Cookbook tool: which calls pay the most premium per unit of assignment risk right now. Official app template: Covered Call Yield.
What the report computes
- Annualized static yield: premium as a share of spot, scaled to a year.
- OTM cushion — how far the stock can rise before the strike is touched.
- Delta as the conventional rough proxy for finishing in the money, plus open interest.
What it does not claim
- Premium is the settlement close; a seller transacts at the bid, so every yield shown is an upper bound.
- Static yield assumes the call expires worthless and models no assignment, early exercise or dividend.
- A single-leg screen — the tape cannot link legs, so nothing here is an actual covered call position.
Shows cushion and delta beside the yield, so a headline annualized number is never readable without the assignment risk that produced it.
Frequently asked questions
- Why is the yield an upper bound?
- It is computed from the settlement close. A real seller transacts at the bid, which sits below it, so the premium actually received is lower than the figure shown.
- Is a 100% annualized yield real?
- It is arithmetic, not a forecast. Annualizing one short-dated premium assumes a cycle repeating all year at the same price, and that level of premium usually reflects a name the market expects to move hard.
Related recipes
- IV rank boardAnswer "whose implied vol is rich right now" without already knowing which symbol to check.
- Expected moveAnswer "how far is this name priced to move by Friday" without building a vol surface first.
- Vol surfaceSee whether options are rich or cheap on the surface before you sell or buy premium.
More learning resources
Related glossary
Related personas
The public page explains the report. Run the official template in TradingFlow for a selected completed market session.
Open Covered call yield