Official template · advanced · Volatility
Compare IV30 minus RV20 with its own history.
See whose IV30−RV20 gap is extreme versus that name’s own history, without relabeling vendor HV as realized vol.
The report UI is recreated from the test app's Sep 25, 2026 session, not a live screen. A historical example with music; no narration.
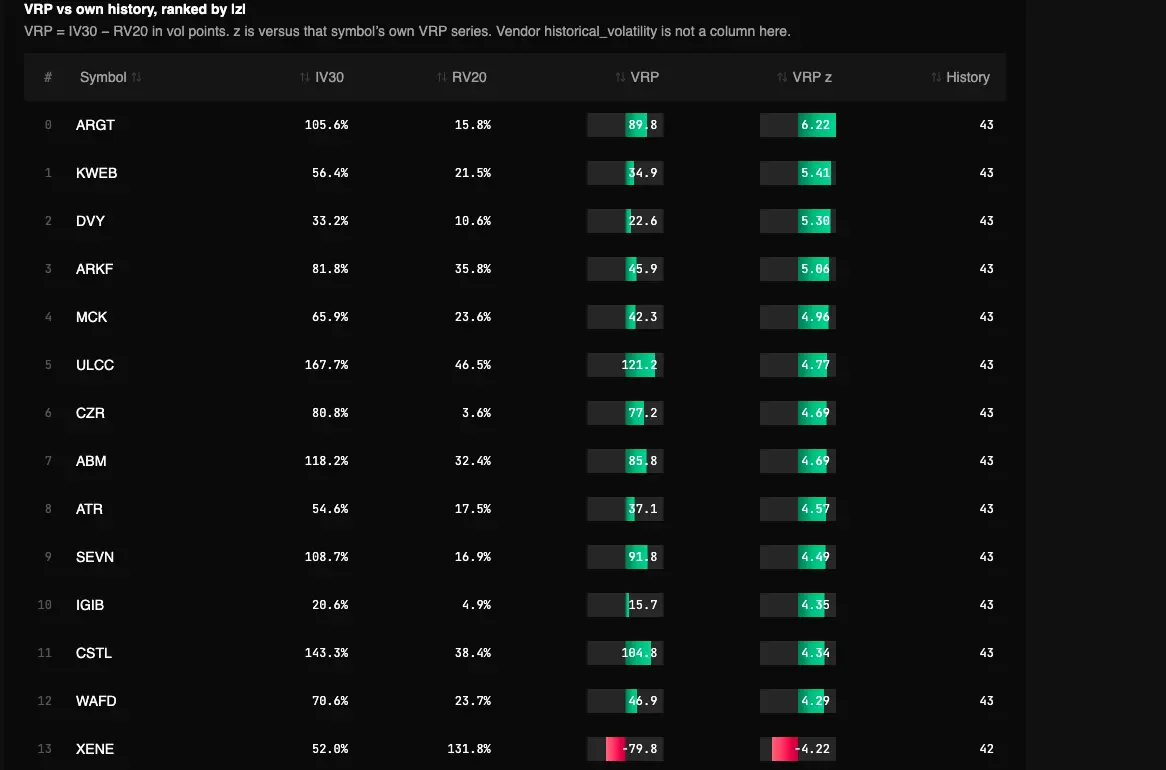
Captured Sep 23, 2026 on testapp.tradingflow.com. This is a historical example; results on this page do not refresh. Swipe across the image to inspect its columns.
- 01IV30 + RV20
- 02Gap vs own history
- 03VRP z-score
Vendor HV is excluded; a z-score is not a trade signal.
Read the output
- 01RV20 = stddevSamp of 20 complete session ln(close/prior close) returns × √252.
- 02VRP = IV30 − RV20 in volatility points. Negative VRP is kept.
- 03z-score of current VRP versus that symbol’s own VRP history in a bounded window.
Keep in mind
Vendor HV is not RV20 and is not used here. That pair is HV vs. RV Divergence Watch.
How to read it
From report to evidence01
Run the VRP tracker
Open Volatility Risk Premium Tracker in Cookbooks.
02
Read z versus the raw gap
A 12-vol-point VRP can be ordinary for that name. The z-score is the unusualness versus its own history.
03
Use Rank for the live column
Rank Symbols still has IV30 − RV20. This cookbook adds the z-score. HV vs RV remains the vendor-HV trap report.
Method and limitations
A paid Cookbook of IV30 − RV20 in vol points, plus a z-score versus that symbol’s own VRP series. RV20 is 20 complete log-returns × √252. Vendor historical volatility is not a column. Not a sell-premium signal. Official app template: Volatility Risk Premium Tracker.
What the report computes
- RV20 = stddevSamp of 20 complete session ln(close/prior close) returns × √252.
- VRP = IV30 − RV20 in volatility points. Negative VRP is kept.
- z-score of current VRP versus that symbol’s own VRP history in a bounded window.
What it does not claim
- Vendor HV is not RV20 and is not used here. That pair is HV vs. RV Divergence Watch.
- A high z is not a documented trading edge or a “sell premium” instruction.
- Names without 20 valid returns or enough VRP history are omitted, not padded.
VRP is IV30 minus governed RV20 (20 log returns × √252), z-scored against that symbol’s own VRP series; vendor historical_volatility is not an input.
Frequently asked questions
- Is the RV20 column vendor HV?
- No. RV20 is 20 complete session log-returns × √252. Vendor historical_volatility is not in this recipe. HV vs. RV Divergence Watch is the report that keeps those two apart.
- Should I sell premium when VRP z is high?
- This recipe does not say so. It describes how wide IV30 − RV20 is versus that name’s own history. Rank’s IV30 − RV20 column is the live comparison.
Related recipes
More learning resources
Related glossary
Related personas
The public page explains the report. Run the official template in TradingFlow for a selected completed market session.
Open VRP tracker